1. Introduction
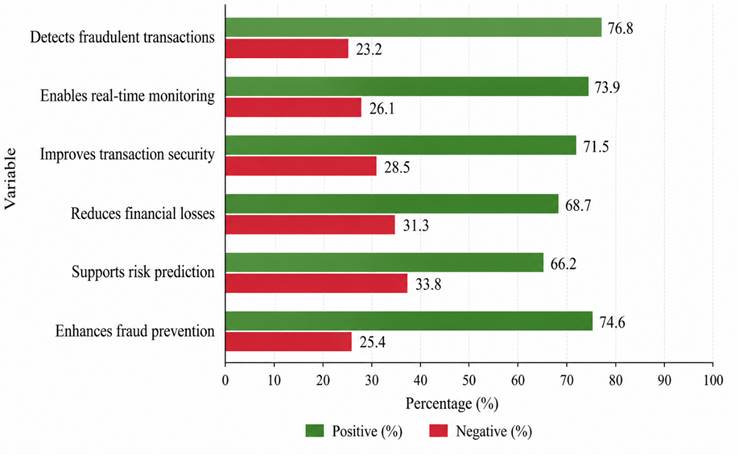
Walk into almost any bank branch today — or, more realistically, open its app — and artificial intelligence is already quietly at work behind the interface, deciding within milliseconds whether a transaction looks like you or looks like someone pretending to be you. That shift did not happen overnight, and it has not been universally welcomed. AI has undeniably reshaped how financial institutions detect fraud, manage risk, and personalize service (Ridzuan et al., 2024), and a good deal of that reshaping has been genuinely useful: algorithms that once needed hours to flag suspicious activity can now do it in real time, narrowing what used to be a fairly generous window for fraud to slip through (Mytnyk et al., 2023). And yet the same systems that make banking faster and, arguably, safer also pull in enormous volumes of personal and financial data — and it is here, in that quiet accumulation, that unease tends to creep in (Zhao & Zhang, 2021).
It is worth pausing, briefly, on why this matters more now than it might have five or ten years ago. Machine-learning models can sift through transaction histories, spending patterns, and behavioral signals far faster than any rule-based system, catching anomalies a human analyst might otherwise miss entirely (Khaifa et al., 2021). That capability is not seriously in dispute. What remains far less settled, though, is what happens around the edges of that capability: who is accountable when a model gets it wrong, whether its reasoning can be explained to a regulator or an ordinary customer, and whether the institutions deploying these tools are doing so within some coherent ethical framework rather than simply because the technology happens to exist (Turksen et al., 2024). Responsible AI governance — a phrase that can sound almost bureaucratic until one sits with what it actually demands — asks banks to hold transparency, accountability, fairness, and security together at once, not as separate boxes to tick but as an integrated discipline (Aldboush & Ferdous, 2023).
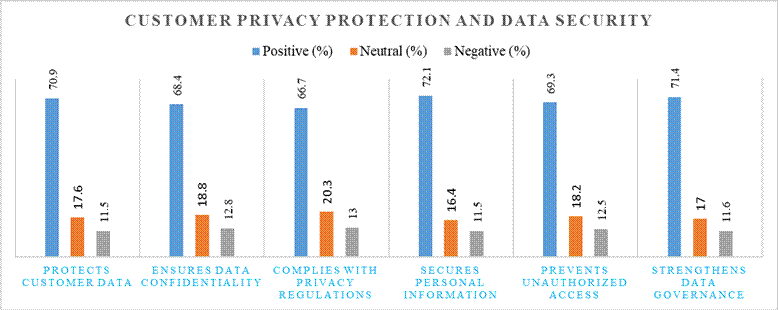
Privacy sits close to the center of this conversation, arguably closer than fraud detection itself. Predictive, personalized banking services simply cannot function without continuous access to customers' financial and behavioral data (Basit et al., 2020; Tao et al., 2019), and that dependency creates real exposure — to breaches, to misuse, to the slow erosion of confidence that follows once people sense their information is being handled carelessly (Mutimukwe et al., 2019; Varma et al., 2022). Banks that get this wrong do not merely risk regulatory penalties; they risk something harder to rebuild, namely customers' willingness to keep sharing information at all (Lui & Lamb, 2018).
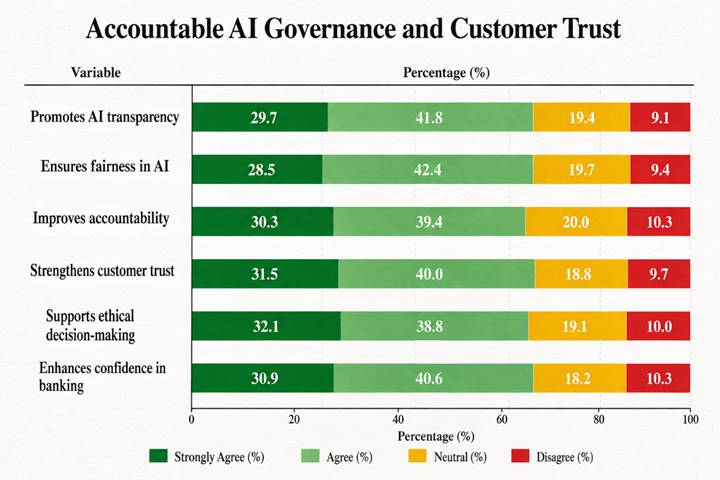
And that, in the end, is where trust enters the picture — not as an afterthought, but as the variable that arguably determines whether any of the rest of this actually works. Customers who doubt the fairness or transparency of an AI system are unlikely to embrace it, however technically sophisticated it might be (Garcia-Segura, 2024). Trust, in other words, is not merely a pleasant byproduct of good governance; it may be the mechanism through which governance translates into adoption, and adoption into the long-term data-sharing relationship banks depend on (Rahahleh et al., 2021).
Despite how central these three threads — fraud detection, privacy protection, and trust — appear to be, the literature has tended to treat them as separate conversations rather than as parts of one interconnected system (Enholm et al., 2021). Fewer studies still have asked the people actually operating inside these systems — bankers, fintech professionals, compliance staff — what they believe is happening on the ground. This study attempts to close part of that gap. Drawing on survey responses from 165 banking, fintech, information-technology, and financial-services professionals across the United States, it examines how AI-enabled fraud detection and privacy protection relate to customer trust under a responsible-governance lens, with the broader aim of offering both empirical grounding and practical direction for banks, technology vendors, and policymakers navigating this fast-moving terrain.